


Why Shiseido, Puig and Henkel All Posted Strong H1 Results
Three of Europe’s most closely watched beauty groups reported first-half 2026 earnings within days of each other in early August, and their numbers describe three structurally different businesses inside the same market. Shiseido’s profit surge came from cost discipline, not demand; Puig’s growth came from category mix; Henkel’s came from acquisitions integrated mid-year. For EU retail buyers building H2 assortments, that distinction matters more than the shared headline of “strong H1.”
| Company | H1 2026 Revenue | Key Profit Metric | Primary Growth Driver |
|---|---|---|---|
| Shiseido | −0.2% (flat) | Core operating profit +90.1% to ¥44.4bn | Cost cuts and restructuring |
| Puig | +4.4% to €2.354bn | Adjusted EBITDA +3.2% to €460m | Category mix (Makeup +9.1%) |
| Henkel Hair | +4.2% organic, €1.7bn sales | Group operating profit +0.3% to €1.62bn | M&A (OLAPLEX, Not Your Mother’s) |
1. Shiseido’s Profit Rebound Is a Sales Story
Shiseido’s H1 2026 core operating profit rose 90.1% year-on-year to ¥44.4 billion (approximately $281.7 million), while operating profit climbed 131.8% to ¥41.9 billion and interim net profit attributable to owners of the parent roughly tripled to ¥29.7 billion. Net sales increased 6.2% to ¥499.0 billion on a reported basis; on a like-for-like basis, excluding currency effects and business transfers, sales were essentially flat, down 0.2%. That gap between reported and like-for-like growth is the number worth reading closely; it means the profit improvement came almost entirely from restructuring and cost control rather than from consumers buying more Shiseido product.
The regional detail confirms it. Asia Pacific grew 2% in H1, and China and Travel Retail sales rose 10% on a reported basis while like-for-like sales there slipped slightly; Americas and EMEA sales each declined 1%, with the company citing stronger competition and ongoing challenges with select brands. Shiseido said its Americas business is “steadily progressing towards profitability”, which is executive language for: the region is still not profitable, but the losses are shrinking on schedule. For a European buyer, the practical read is that Shiseido has room to defend margin through further SKU rationalization under its “Power Duos” strategy, which concentrates investment on Clé de Peau Beauté, NARS and a small number of hero products; ranges built around peripheral Shiseido lines carry more discontinuation risk over the next 12–18 months than ranges built around the brands the company is visibly protecting.

2. Puig’s Growth Is Concentrated in Makeup, Not Broad-Based Despite the Language
Puig reported H1 2026 net revenue of €2.354 billion, up 4.4% like-for-like (2.4% reported), with adjusted EBITDA rising 3.2% to €460 million and adjusted net profit up 5.2% to €260 million. CEO José Manuel Albesa said the results reflected the company “gaining market share across categories and geographies”, which in practice means the growth is real but unevenly distributed across the three divisions.
Makeup, led by Charlotte Tilbury, grew 9.1% like-for-like to €359 million in revenue, the fastest of the three segments; but Makeup’s operating profit fell to €6.5 million from €12.1 million a year earlier, an operating margin of just 1.8%, as Puig increased advertising and promotional spend behind the brand. For a retail buyer, strong sell-through and heavy brand investment usually means better in-store support and launch cadence near-term, but it also means Puig is currently prioritizing market share over segment profitability in color cosmetics: a stance that isn’t guaranteed to hold if it doesn’t convert to margin by FY2027.

Skincare grew only 2.3% to €279 million, with operating profit falling to €4.2 million from €21.0 million, as premium skincare demand softened even as Uriage held share. Fragrance and Fashion, still 73% of group revenue at €1.7 billion, grew a steadier 3.8% and delivered the group’s real profit, with operating profit rising to €329 million from €299 million at a 19.2% margin. Geographically, Asia-Pacific was the standout, up 20.9% like-for-like versus 2.6% in the Americas; that APAC strength, alongside Shiseido’s China stabilization, is worth noting for any EU retailer weighing shelf space for Asian-origin beauty categories (K-beauty included) against slower-growing Western prestige skincare. Puig has also confirmed it ended merger talks with Estée Lauder, opting to remain independent, which removes one source of ownership uncertainty for accounts carrying Puig brands.
3. Henkel Hair’s 4.2% Growth Is Real But It’s Covering for the Rest of the Portfolio
Henkel’s group organic sales rose 3.2% in H1 2026 on reported revenue of €10.35 billion (down 0.5% nominally), with operating profit up a modest 0.3% to €1.62 billion. The raised full-year organic growth guidance (now 1.5%–3.5%, up from 1%–3%) was driven largely by Adhesive Technologies, up 4.5% organically, not by the consumer-facing side of the business that wholesale buyers actually stock.
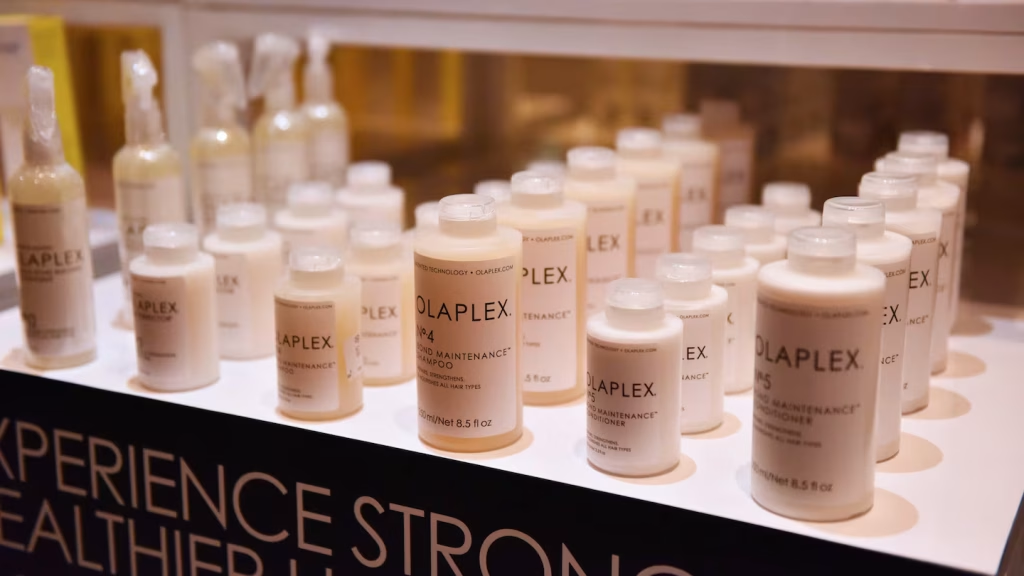
Within Consumer Brands, which grew just 1.7% organically on reported sales of €4.7 billion (down 3.5% nominally), Hair Care was the standout, delivering 4.2% organic growth on €1.7 billion in sales. That performance was built on acquisitions closed mid-year: Henkel completed its $1.4 billion purchase of OLAPLEX, adding roughly €370 million in annual sales and making Henkel the global number two in professional hair care, and finalized its purchase of Not Your Mother’s in April, adding scale in North American mass hair. CEO Carsten Knobel described the strategy as reflecting “a clear focus on purposeful growth”, which is executive shorthand for: buying revenue growth that the base portfolio isn’t generating on its own.
Henkel’s wider M&A program, worth roughly €5 billion across five deals, is running on the following timeline:
- Not Your Mother’s: closed April 2026, North American mass hair care
- OLAPLEX: closed 2026, $1.4bn deal, ~€370m annual sales, premium/professional hair
- ATP Adhesive Systems: closed, Adhesive Technologies division
- Wetherby Laroc: closed, Adhesive Technologies division
- Stahl Group: expected to close in H2 2026, Adhesive Technologies division
Strip Hair Care out of Consumer Brands, and the remaining categories (Laundry & Home Care and other personal care) grew closer to 0.5% in Q1, the underlying figure analysts have flagged as the real story behind the headline. The acquisitions are adding genuine revenue, but they also mean two newly integrated hair brands now carry a disproportionate share of Henkel’s consumer growth. For a European distributor or salon-channel buyer stocking Schwarzkopf, Got2b, or the newly added OLAPLEX and Not Your Mother’s lines, that concentration is worth watching heading into contract renewals; Henkel has said its five-deal, roughly €5 billion M&A program is expected to add about €2 billion in annual revenue by 2030, with meaningful integration work (and likely some SKU and pricing rationalization) still ahead through H2 2026 and into 2027.
4. What Three Different Growth Stories Mean for H2 Range Planning
None of these three results argues for the same buying decision:
- Shiseido: defensive profit growth funded by cost cuts, not demand; favor the brands under “Power Duos” and treat peripheral SKUs as discontinuation risks.
- Puig: expand color cosmetics space behind Charlotte Tilbury’s sell-through; apply more scrutiny to new premium skincare listings from any prestige house.
- Henkel Hair: confidence in the category generally, reinforced by Puig’s and Shiseido’s own APAC momentum, but caution on pricing and MOQs for brands still mid-acquisition.
The common thread is that reported H1 “strength” arrived through three structurally different levers: cost control, category mix, and M&A. A buyer reading only the headline growth percentage would draw the same conclusion about all three companies, and would be wrong about at least two of them.
For EU retailers and distributors mapping H2 2026 assortments across fragrance, color cosmetics and haircare, understanding which growth is structural and which is acquisition-dependent is more useful than the headline number alone. B Futurist’s sourcing team tracks these shifts across our supplier base, including our expanding K-beauty distribution lines, and can walk through current availability and terms for any of the categories above.
FAQ
Does Shiseido’s profit growth mean better wholesale terms are coming? Not directly. The improvement is a cost and mix outcome rather than a demand outcome, so it’s unlikely to translate into more aggressive trade support in the near term. Buyers are more likely to see continued focus on the brands under the “Power Duos” strategy, with slower-moving lines facing a higher risk of range reduction rather than promotional investment.
Should retailers expect price changes on Henkel hair brands after the OLAPLEX and Not Your Mother’s acquisitions? Price and term changes typically follow the first full integration cycle rather than the acquisition date itself, so any adjustment is more likely from late 2026 into 2027 once Henkel completes the operational integration work it has flagged for H2. Buyers with existing hair care agreements should confirm current terms are locked through any transition period.
Is Puig’s makeup growth a reason to expand color cosmetics assortments? The sell-through data supports it: Charlotte Tilbury’s 9.1% like-for-like growth and continued market share gains are demand signals, not just brand-side promotion; but the segment’s thin 1.8% operating margin means Puig is currently subsidizing that growth with marketing spend. Buyers should treat sustained retail support as conditional on that investment continuing rather than guaranteed long-term.
Why did Puig’s skincare segment slow while makeup and fragrance grew? Premium skincare demand broadly softened across the period, and operating profit in the segment fell as investment continued despite the slower top line. Uriage’s continued share gains were the exception rather than the rule within the division, which suggests selectivity within premium skincare listings matters more right now than broad category expansion.
Does Puig’s Asia-Pacific growth signal anything for K-beauty sourcing decisions? It’s one more data point, not proof on its own. Puig’s 20.9% like-for-like growth in the region, alongside Shiseido’s China stabilization, indicates sustained consumer appetite for Asian beauty categories broadly, which supports the case for expanding K-beauty ranges even though neither company sells Korean beauty brands directly.
Are these three companies a reliable barometer for the wider EU beauty wholesale market? They’re useful as category-level signals (fragrance, prestige makeup, and professional/consumer hair specifically), but each result is shaped by company-specific factors (restructuring, M&A, brand mix) rather than pure category demand. Buyers should treat them as directional evidence to combine with their own sell-through data, not as a standalone forecast.
Sources
- Cosmetics Business. “Shiseido’s profits surge 90% as turnaround plan takes shape.” https://cosmeticsbusiness.com/shiseido-s-profits-surge-90-as-turnaround-plan-takes
- BigGo Finance. “Shiseido’s Interim Net Profit Surges 3.1x; Structural Reforms Pay Off, Boosting Confidence in Full-Year Target Achievement.” https://finance.biggo.com/news/c6e00bab-e0da-4bcd-b82c-933f5bbab76d
- Puig. “Puig Reports Strong H1 Performance, Gaining Market Share.” https://www.puig.com/en/newsroom/puig-strong-h1-performance-gaining-market-share/
- Global Cosmetics News. “Puig Reports Strong First-Half 2026 Growth as Premium Beauty Market Share Expands.” https://www.globalcosmeticsnews.com/puig-reports-strong-first-half-2026-growth-as-premium-beauty-market-share-expands/
- Cosmetics Business. “Henkel raises full-year guidance on ‘strong’ H1 2026, despite softer consumer brands performance.” https://cosmeticsbusiness.com/henkel-raises-full-year-guidance-on-strong-h1
- Investing.com. “Henkel H1 2026 slides: upgraded outlook on strong growth, M&A wins.” https://ca.investing.com/news/company-news/henkel-h1-2026-slides-upgraded-outlook-on-strong-growth-ma-wins-93CH-4780361
- Global Cosmetics News. “Global Cosmetics News – Weekly Review | Week 32, August 2026.” https://www.globalcosmeticsnews.com/global-cosmetics-news-weekly-review-week-32-august-2026/
- Filiberto Amati. “Henkel’s Consumer Business Grew 0.5% Without Hair Care.” https://www.filibertoamati.com/p/henkels-consumer-business-grew-05